Naples Foreclosures and Bank-Owned Homes
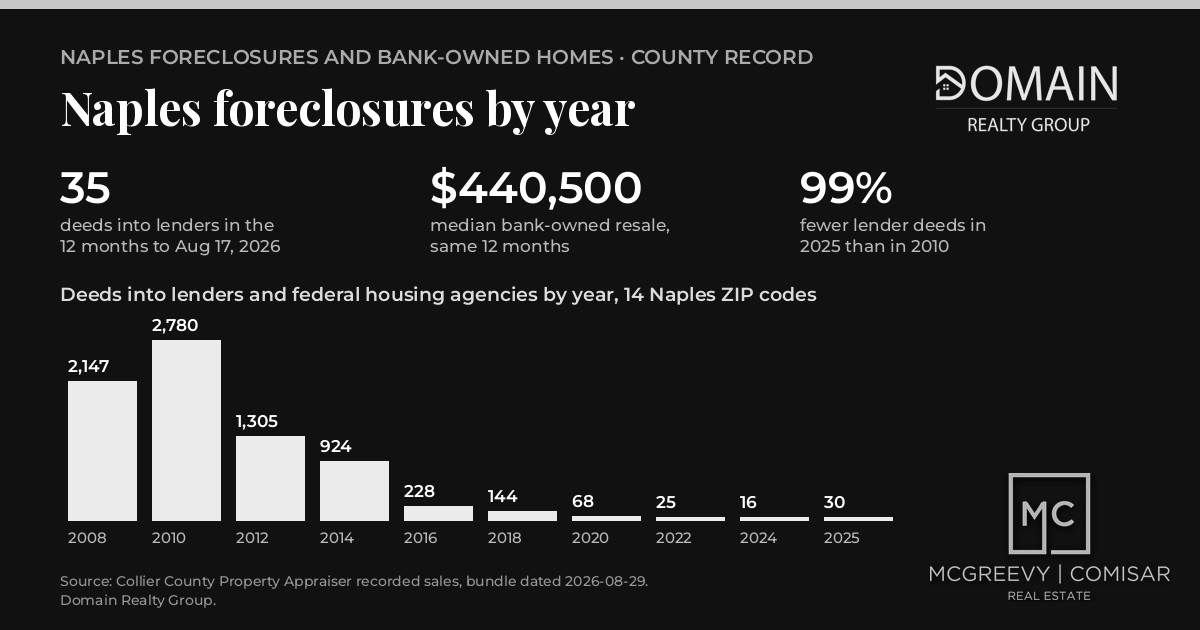
Foreclosures in Naples are near record lows. Collier County recorded 35 residential deeds into lenders and federal housing agencies in the 14 Naples ZIP codes in the 12 months to August 17, 2026, against 2,780 in 2010. Florida, by contrast, had the highest foreclosure rate in the U.S. in the first half of 2026: 1 in 373 housing units, per ATTOM.
This page is the distressed-property section of our Naples homes for sale and communities guide. It links live listings, sets out what the Collier County record says about Naples foreclosures by year, ZIP code and property type, and walks through every route to a distressed Naples home, from the Clerk’s courthouse auction and tax deed sales to bank-owned, HUD, Fannie Mae and VA homes, online auctions and short sales, plus the checks that cost buyers most when skipped. Updated October 2026.
By Jesse McGreevy and Marc Comisar, Domain Realty Group, the #1 team in Southwest Florida since 2012.
Key takeaways
- Collier County recorded 35 residential deeds into lenders and federal housing agencies in Naples ZIP codes in the 12 months to August 17, 2026, against 2,780 in calendar 2010 and 30 in calendar 2025.
- Of those 35, 16 were condominiums, 13 single-family homes, 4 mobile homes and 2 small multifamily buildings; ZIP 34112 in East Naples led with 10, then 34120 with 7.
- Lenders resold 16 Naples homes in the same 12 months at a $440,500 median, against a $615,000 median for 8,129 qualified home sales.
- ATTOM counted 27,494 Florida properties with a foreclosure filing in the first half of 2026, up 32.65 percent, and Florida repossessions rose from 1,126 to 2,070.
- Collier foreclosure sales are held in person at the Main Courthouse; on a $400,000 winning bid the registry fee and deed stamps add $8,807.50.
- Collier tax deed sales run Mondays at 1 p.m., in person, with a nonrefundable deposit of 5 percent or $200, whichever is greater, and the balance due within 24 hours.
Naples foreclosures and bank-owned listings for sale right now
Bank-owned homes and short sales in Naples sell through the same Southwest Florida MLS as every other home, so the fastest way to find them is a filtered search sorted by price. With only 16 lender resales recorded in Naples ZIP codes in the 12 months to August 17, 2026, they surface a few at a time.
Data updated: October 2026.
- Naples homes listed under $400,000, lowest price first
- Naples condos listed under $300,000, the band where most lender-owned condos land
- Naples single-family homes listed under $500,000
- Golden Gate Estates single-family homes for sale, the acreage side of ZIP 34120
- Naples listings added in the last 7 days, where a new bank-owned listing shows first
- Naples condos listed in the last 7 days
Bank-owned and short-sale status is written into each listing’s remarks (“bank owned”, “REO”, “short sale”, “third-party approval”), and we flag those listings for buyers on request. Listings refresh from the MLS through the day. For the wider market, see Naples condos for sale and land for sale in Naples.
How many foreclosures are there in Naples?
Collier County recorded 35 residential deeds into lenders and federal housing agencies in the 14 Naples ZIP codes in the 12 months to August 17, 2026. That is about one for every 232 qualified home sales in the same window (8,129), and 99 percent below the 2,780 recorded in calendar 2010, the peak of the last crash.
Data updated: October 2026.
How we count it. We tracked every recorded deed on residential parcels in the 14 Naples ZIP codes in the Collier County Property Appraiser public sales and parcel files (bundle dated August 29, 2026). A “deed into a lender” is a transfer whose first grantee is a bank, servicer, mortgage trust, credit union, Fannie Mae, Freddie Mac, HUD or the VA: the certificate of title the Clerk issues when the lender wins its own sale, or a deed in lieu.
Why it is a floor. A sale won by a third-party bidder is not counted. Trusts, individuals and title companies were excluded after false matches, and the 12 association deeds in the window were dropped, since most were interval units at the Kings Crown condo motel on Gulf Shore Drive. A “lender resale” is the parcel’s next sale to a non-lender above $1,000.
| Year | Deeds into lenders | Lender resales | Median lender resale | Qualified home sales | Qualified median |
|---|---|---|---|---|---|
| 2008 | 2,147 | 1,123 | $143,000 | 4,705 | $300,000 |
| 2009 | 2,242 | 2,218 | $97,150 | 5,090 | $233,100 |
| 2010 | 2,780 | 1,690 | $100,750 | 7,948 | $200,000 |
| 2011 | 1,594 | 1,472 | $102,000 | 8,068 | $205,000 |
| 2012 | 1,305 | 1,100 | $120,000 | 9,030 | $230,000 |
| 2014 | 924 | 877 | $164,900 | 10,411 | $300,000 |
| 2016 | 228 | 247 | $205,000 | 11,028 | $330,000 |
| 2018 | 144 | 126 | $248,750 | 11,626 | $340,000 |
| 2020 | 68 | 85 | $250,000 | 14,775 | $360,000 |
| 2022 | 25 | 20 | $425,000 | 11,936 | $544,250 |
| 2023 | 15 | 15 | $311,600 | 10,542 | $595,000 |
| 2024 | 16 | 11 | $450,000 | 9,488 | $610,000 |
| 2025 | 30 | 13 | $480,000 | 9,211 | $595,000 |
| 2026 (to Aug 17) | 27 | 12 | $445,500 | 5,765 | $605,000 |
Source: Collier County Property Appraiser public sales and parcel files (bundle dated August 29, 2026), residential parcels, 14 Naples ZIP codes; 2026 runs to August 17. Qualified sales are Florida Department of Revenue arm’s-length sales; lender resales are mostly coded unqualified, so the columns are separate counts.
In 2009 the county recorded 2,218 lender resales, at a $97,150 median, against 5,090 qualified sales. Lender deeds ran 15 to 25 a year from 2022 through 2024; the 30 in 2025 and 27 through August 17, 2026 mean Naples foreclosures are rising off a very low base.
What kind of Naples homes are being foreclosed?
Condos lead. Of the 35 deeds into lenders in the 12 months to August 17, 2026, 16 were condominium units (46 percent), 13 single-family homes, 4 mobile homes and 2 small multifamily buildings (see the condo section).
Who takes title after a Naples foreclosure?
The Secretary of Veterans Affairs took 4 of the 35 (VA-guaranteed loans) and HUD took 2 (FHA-insured loans). Fannie Mae took 3, and Freddie Mac also appears among the grantees. Private-label mortgage trusts took several (COLT 2021-4 took 2), and the rest went one each to banks, servicers and credit unions such as Bank of America, PennyMac and Suncoast Credit Union.
What do bank-owned homes sell for in Naples?
Lenders resold 16 Naples homes in the 12 months to August 17, 2026 at a $440,500 median, from $99,800 to $3,000,000, against a $615,000 median for 8,129 qualified home sales. The mix differs (more condos, more East Naples), so read it as a price band, not a discount. The median lender held a home about 7 months before reselling it.
How does the county count compare with outside data?
ATTOM’s public Collier County page showed 40 properties with a foreclosure filing in June 2025, 23 starts and 2 completed foreclosures (REOs), and 192 filings from January to June 2025. Two REOs a month matches the county’s 30 lender deeds in 2025; most filings never reach a deed.
Are foreclosures rising in Naples in 2026?
Slightly, and far less than in Florida. Naples deeds into lenders rose from 16 in 2024 to 30 in 2025 and 35 in the 12 months to August 17, 2026, per Collier County records, while Florida properties with a filing rose 32.65 percent to 27,494 in the first half of 2026 (ATTOM), the highest state rate in the U.S.
Data updated: October 2026.
What is happening across Florida?
ATTOM’s midyear 2026 report put Florida first among states at 1 in 373 housing units with a filing, with 20,358 foreclosure starts, second only to Texas. Florida bank repossessions rose from 1,126 in the first half of 2025 to 2,070 in the first half of 2026, up 83.8 percent. The worst metros are next door: Punta Gorda had the highest metro rate in the U.S. at 0.50 percent, then Lakeland at 0.48 percent and Cape Coral-Fort Myers at 0.35 percent. The Naples metro is not in ATTOM’s ranked lists.
Why are Naples foreclosures still so low?
Prices have held, so owners who fall behind can usually sell first. Florida Realtors put the Naples-Immokalee-Marco Island single-family median at $785,000 in September 2026, up 1.6 percent, and the condo and townhouse median at $432,500, up 4.2 percent. Nationally, 2025 filings were 87 percent below the 2010 peak.
What could push Naples foreclosures higher?
Condo assessments, insurance and tax bills, and FHA loans. The Mortgage Bankers Association’s second-quarter 2026 survey showed national delinquency of 11.79 percent on FHA loans, up 122 basis points in a year, against 2.72 percent on conventional and 4.89 percent on VA loans. The 6 VA and HUD deeds in Naples show that stress locally.
How bad was the last Naples foreclosure crisis?
RealtyTrac counted 9,341 Collier County properties with a filing in 2008, up 234 percent and 4.98 percent of housing units. The Naples-Marco Island metro rate hit 3.64 percent in the first half of 2009, 12th worst in the nation. The Naples single-family median fell from $220,000 in January 2010 to $167,000 in January 2011, down 24 percent, and the condo median from $160,000 to $141,000.
Where in Naples do foreclosures happen?
East Naples leads. Of the 35 deeds into lenders recorded in Naples ZIP codes in the 12 months to August 17, 2026, ZIP 34112 had 10 and 34120 had 7, together almost half. Four Naples ZIP codes recorded none: 34102, 34105, 34116 and 34117, per the Collier County record.
Data updated: October 2026.
| Naples ZIP | General area | Deeds into lenders, 12 months to Aug 17, 2026 |
|---|---|---|
| 34112 | East Naples | 10 |
| 34120 | Golden Gate Estates and the Orangetree side | 7 |
| 34114 | East Naples toward Marco Island and Fiddler’s Creek | 4 |
| 34104 | Golden Gate and central Naples | 4 |
| 34109 | North Naples | 3 |
| 34110 | North Naples near Vanderbilt and Wiggins Pass | 2 |
| 34119 | North Naples east of I-75 | 2 |
| 34103 | Park Shore and the Moorings | 1 |
| 34113 | Lely and the Royal Harbor area | 1 |
| 34108 | Vanderbilt Beach and Pelican Bay | 1 |
| All 14 Naples ZIPs | 35 |
Source: Collier County Property Appraiser public sales and parcel files (bundle dated August 29, 2026). ZIP labels are general guides, not community boundaries, and no foreclosure here is attributed to a named community.
Resales follow the same map: of the 16 lender resales in the same window, 6 were in 34112, 2 each in 34102, 34109 and 34117, and 1 each in 34103, 34104, 34114 and 34120; 7 were single-family homes, 6 condos and 3 other types. For Estates homes, the well, septic and flood checks on our Naples land for sale page apply to a foreclosure too.
What are the ways to buy a distressed home in Naples?
There are seven routes, and they differ most on cash, inspection and title. A Collier courthouse auction needs a 5 percent deposit and the balance by 10:30 a.m. the next business day with no inspection, while a bank-owned MLS listing can be financed and inspected like any resale.
Data updated: October 2026.
| Route | Where it happens | Financing | Can you inspect? | Title you get | Cash and timing | Who it suits |
|---|---|---|---|---|---|---|
| Collier courthouse auction | Main Courthouse, in person | Cash; the lender usually wins with a credit bid | No; sold “as is” | Clerk’s certificate of title | 5% deposit; balance by 10:30 a.m. next business day | Cash investors |
| Bank-owned (REO) listing | MLS, via the lender’s broker | Any loan the home qualifies for | Yes, as is | Usually special warranty deed | Per contract and addendum | Owner-occupants |
| HUD, HomePath and VA homes | HUD Home Store, HomePath, VRM | FHA, 203(k), VA Vendee | Yes, as is | Agency deed | 30-day owner-occupant window on insured HUD homes | Owner-occupants |
| Online auctions (Auction.com, Xome) | Online | Often cash only | Often no | Per platform agreement | Buyer’s premium (Xome: typically 5% or $2,500) | Experienced buyers |
| Short sale | MLS; owner holds title | Any loan that can wait | Yes, after approval | Deed from owner | 90-day approval default, close 45 days after | Patient buyers |
| Pre-foreclosure from the owner | Private | Any | By agreement | Deed from owner; liens paid | 3-business-day cancel right if owner keeps an interest | Investors with an attorney |
| Collier tax deed sale | Courthouse, Mondays 1 p.m. | Cash | No | Tax deed, no title guarantee | 5% or $200 deposit; balance in 24 hours | Cash investors |
Who should choose which route?
A buyer who needs a mortgage and an inspection should start with bank-owned MLS listings, HUD and HomePath homes and short sales. A cash buyer who can research title and buy sight unseen can add the courthouse auction, tax deeds and online auctions. In Naples most distressed homes end up as bank-owned listings: lenders took 35 homes in the latest 12 months and resold 16.
How does a Collier County foreclosure auction work?
In person, at the courthouse. The Collier County Clerk holds every foreclosure sale at the Main Courthouse, 3315 Tamiami Trail East, Naples, FL 34112, generally 20 to 35 days after the final judgment. The winner posts a 5 percent deposit, pays the balance by 10:30 a.m. the next business day, and gets a certificate of title after a 10-day objection window.
Data updated: October 2026.
Where and when does the sale happen?
Florida is a judicial foreclosure state, and s. 45.031(1)(a) sets the sale “not less than 20 days or more than 35 days” after the final judgment unless the plaintiff consents to later. Unlike the many Florida counties that sell online, the Collier Clerk’s foreclosure sales page (updated October 5, 2026) says all sales are held at the Main Courthouse, annex side, in the first-floor Customer Service Department multipurpose room; its online calendar (Court Events, event type “Foreclosure Sales”) is for finding sales, not bidding. The owner can cure until the certificate of sale, so check the docket the morning of the sale.
What do you pay, and when?
The winner posts a 5 percent advance deposit, applied to the final payment. The balance, the court registry fee and costs in the judgment are due by 10:30 a.m. the first business day after the auction unless the judgment says otherwise. The registry fee is 3 percent of the first $500 plus 1.5 percent of the rest, and documentary stamp tax on the certificate of title is $0.70 per $100 (s. 201.02(1)(a)), paid before the certificate issues. A winner who does not pay loses the sale and, under s. 45.031(3), the sale costs come out of the deposit.
Worked example: a $400,000 winning bid
| Item | How it is figured | Amount |
|---|---|---|
| Winning bid | $400,000.00 | |
| Deposit at the sale | 5% of the bid, credited to the final payment | $20,000.00 |
| Court registry fee | 3% of the first $500 ($15.00) plus 1.5% of the remaining $399,500 ($5,992.50) | $6,007.50 |
| Documentary stamp tax | $0.70 per $100 of $400,000 | $2,800.00 |
| Costs beyond the bid | registry fee plus stamps | $8,807.50 |
| Total paid to the Clerk | bid plus costs beyond the bid | $408,807.50 |
| Due the next business day | balance of the bid ($380,000) plus the registry fee, with stamps before the certificate of title | $388,807.50 |
The example uses only the Clerk’s published fees; judgment costs, recording fees, past-due taxes and association balances come on top.
What happens after you win?
The Clerk files a certificate of sale, usually within a day and after full payment. Any party has 10 days to object to the bid (s. 45.031(8)); if none does, the Clerk files the certificate of title and title passes.
Can the owner get the home back after the sale?
No. Under s. 45.0315 the owner or a subordinate interest holder can cure only until the later of the certificate of sale or a time set in the judgment; “otherwise, there is no right of redemption.” And s. 702.036 treats a later attack on the judgment as a money claim only, without undoing title, when an unaffiliated buyer paid value and the statute’s conditions are met.
What survives the foreclosure sale?
The sale clears the plaintiff’s lien and the junior interests named in the case, and the Clerk sells “as is.” Check these before bidding:
- A senior mortgage. When the plaintiff is a second mortgage holder or an association, ask the title company whether a recorded first mortgage stays on the property.
- Property taxes. Under s. 197.122, taxes are “a first lien, superior to all other liens,” so a buyer inherits unpaid taxes.
- Federal tax liens. The IRS can redeem a properly noticed lien for 120 days after the sale by repaying the buyer’s price plus 6 percent interest and certain expenses, per the Internal Revenue Manual.
- Condo and HOA balances. A new owner is “jointly and severally liable with the previous owner for all unpaid assessments” (s. 718.116(1)(a); s. 720.3085(2)(b) for HOAs). The cap of 12 months of assessments or 1 percent of the original mortgage debt, whichever is less, is written for a first mortgage lender that named the association in the case, not for a third-party bidder, so plan on the full balance.
- Code and municipal liens. Code fines become liens once recorded (s. 162.09), and the City of Naples treats unpaid utility bills as liens. Run the searches in the checklist below.
Who removes the occupants?
The buyer, through a writ of possession after the certificate of title. Under s. 83.5615 the successor after a foreclosure must give a bona fide tenant at least 90 days’ notice to vacate, and a tenant with a pre-foreclosure lease may stay to its end unless the buyer will live there. The former owner and the owner’s spouse, child or parent are not bona fide tenants.
What happens to surplus money from the sale?
Money left after the judgment and timely junior claims is presumed, under s. 45.032, to belong to the owner of record when the lis pendens was filed, and is presumed unclaimed one year after the sale. It is never the bidder’s money.
How do Collier County tax deed sales work?
A tax deed sale forces a sale for unpaid property taxes. Once a tax certificate has gone unredeemed for 2 years from April 1 of its issue year, its holder can apply for a tax deed, and the Collier Clerk auctions the property in person on Mondays at 1 p.m., for a nonrefundable 5 percent or $200 deposit and the balance within 24 hours.
Data updated: October 2026.
How does the tax certificate sale start it?
When taxes go unpaid, the Collier County Tax Collector sells a tax certificate at its annual online sale. Buyers pay the taxes and bid the interest rate down in quarter-point steps (s. 197.432) from the 18 percent maximum, as tax collectors such as Hillsborough County explain to bidders. The owner can redeem any time before a tax deed issues by paying the face amount plus interest and costs (s. 197.472).
When can a tax deed be applied for?
Under s. 197.502, a holder other than the county may apply “after 2 years have elapsed since April 1 of the year of issuance,” for a $75 Tax Collector fee plus online costs. The Clerk records a notice of application, effective one year, and titleholders, lienholders and mortgagees of record get notice so they can pay first. The Collier Clerk’s tax deed sales page advertises each sale for four consecutive weeks.
How does the Clerk’s tax deed auction run?
Auctions run Mondays as needed at 1:00 p.m. in the first-floor multipurpose room of the Courthouse Annex, 3315 Tamiami Trail East, in person or through a representative, with no phone, mail or internet bids. The high bidder pays a nonrefundable deposit of 5 percent or $200, whichever is greater, and the balance plus recording fees and stamps within 24 hours, excluding weekends and holidays (s. 197.542); a missed payment cancels the bid and the sale is readvertised. On a $50,000 bid the deposit is $2,500; on a $3,000 bid the $200 minimum applies. Collier sales usually carry one to a handful of parcels, mostly vacant land and condominiums.
What is the opening bid, and why is homestead different?
Under Rule 12D-13.063 of the Florida Administrative Code, the opening bid adds the certificates, delinquent and current taxes, the Tax Collector’s, sheriff’s and Clerk’s fees, and interest at 1.5 percent a month; after November 1, the Clerk includes current-year county taxes. On homestead property, s. 197.502(6) adds one-half of the latest assessed value. With no higher bid, the certificate holder takes the property.
What title does a tax deed give you?
A new title, sold “as is”: the Clerk warrants nothing about title, zoning, size or improvements, and its property report is not a title search. Ask a title insurer and a Florida real estate attorney what it takes to insure that title, which can include a quiet title action. Former owners and lienholders have 120 days from the Clerk’s notice to claim surplus (s. 197.582).
How do you buy a bank-owned home in Naples?
Through the MLS, like a regular resale. A lender that takes a Naples home at the foreclosure sale hands it to a local listing broker, who lists it on the Southwest Florida MLS; lenders resold 16 Naples homes this way in the 12 months to August 17, 2026. The differences are the bank’s addendum, the as-is terms and the deed.
Data updated: October 2026.
How do banks list REO homes?
A local REO listing broker presents offers to the lender’s asset manager. Fannie Mae homes are marketed through HomePath and Freddie Mac homes through HomeSteps, each with an assigned listing agent, and neither sells directly to buyers. VRM, which sells VA homes, calls its own site a supplement to MLS listings.
What does a bank’s offer process look like?
Expect a lender addendum written to control over the Florida Realtors and Florida Bar contract where they conflict, proof of funds or a pre-approval with the offer, and as-is terms: you may cancel within the inspection period, but the seller need not repair. Ask for utilities on for the inspection.
Does the bank have to disclose defects?
Not the way an owner does. Johnson v. Davis, 480 So. 2d 625 (Fla. 1985), requires a Florida home seller to disclose known material defects that are not readily observable, but Florida real estate attorneys note the duty does not reach a foreclosing lender that never lived in the home. Your inspection, permit search and lien search are your disclosure.
What deed does a bank give, and who pays for title insurance?
Banks usually convey by special warranty deed, which covers only the years the bank owned the home, so an owner’s title policy is essential. In Naples the buyer customarily pays for the owner’s title policy; confirm in the addendum who pays what.
How do HUD homes work?
HUD sells homes from FHA-insured loans through HUD Home Store, with offers through a HUD-registered broker; its Florida asset manager on HUD’s contact sheet (revised January 16, 2025) is Raine and Company, LLC. Under HUD Mortgagee Letter 2022-01, homes marketed as “insured” or “insured with escrow” get a 30-day exclusive period for owner-occupants, government entities and HUD-approved nonprofits; uninsured homes get 5 days. Good Neighbor Next Door sells HUD homes in revitalization areas to full-time law enforcement officers, pre-K through 12 teachers, firefighters and EMTs at 50 percent off list, for 36 months of owner occupancy, secured by a silent second mortgage HUD releases afterward.
How do HomePath and VA homes work?
Fannie Mae’s HomePath First Look gives owner-occupants and some nonprofits an exclusive window before investors; check each listing’s countdown. On Vendee-eligible VA homes, VRM Lending’s Vendee loan is open to veterans and non-veterans, owner-occupants and investors, with no mortgage insurance.
What do online auctions charge?
Xome’s help center says its buyer’s premium “is typically 5% of the winning bid or $2,500, whichever is greater,” added to the bid. Auction.com shows fees on each listing, says most of its properties do not allow traditional financing, and wants the signed agreement, proof of funds and earnest money within one business day.
How do short sales work in Naples?
A short sale is a sale for less than the mortgage balance, and it closes only if every lienholder approves in writing. Under the current Florida Realtors and Florida Bar short sale rider, the approval deadline defaults to 90 days from the contract date and closing to 45 days after approval, so a default short sale can run about four and a half months.
Data updated: October 2026.
What does lender approval involve?
The lender is not a party to the contract and has no duty to approve. The rider (Rider G, Short Sale Approval Contingency, as compiled by Attorneys’ Title Fund Services in August 2025) has the seller obtain the lender’s application within 10 days and return it within 5 more. After the 90-day default deadline either party may cancel with the deposit refunded, the contract ends automatically 30 days after the deadline without approval, and a foreclosure sale first ends it with the deposit refunded. An approval that does not fully waive the lender’s deficiency claim against the seller does not count unless the affected party accepts it in writing.
What should buyers understand about the seller’s side?
Under s. 702.06, a deficiency on owner-occupied property cannot exceed the debt minus the home’s fair market value, and s. 95.11(6)(g) gives a lender one year after the certificate of title or a deed in lieu to sue; a Florida appeals court held in Bush v. Whitney Bank (2017) that the one-year limit does not apply after a short sale, which is why sellers want a written waiver. IRS Topic 431 limits the principal-residence exclusion for forgiven debt to debt discharged before January 1, 2026, or under a written arrangement made before then. Fannie Mae’s Selling Guide sets a 4-year wait after a short sale and 7 years after a foreclosure before a new Fannie-backed loan (2 and 3 years with extenuating circumstances).
Can you buy before foreclosure directly from the owner?
Yes, carefully. Florida’s foreclosure-rescue law, s. 501.1377, covers an “equity purchaser” who buys a home in foreclosure while the owner keeps an interest, such as a lease-back or buy-back. The owner gets a 3-business-day cancel right that cannot be waived, a repurchase price more than 17 percent a year above the buyer’s cost is presumed unconscionable, and violations carry penalties up to $15,000 each. The Florida Attorney General warns owners away from anyone charging an up-front fee for foreclosure help.
Can you finance a foreclosure in Naples?
Yes for bank-owned homes and short sales, no for the courthouse auction, where the balance is due by 10:30 a.m. the next business day. FHA 203(k), Fannie Mae HomeStyle and VA Vendee loans can finance a bank-owned Naples home, and HUD’s Limited 203(k) now covers up to $75,000 of repairs.
Data updated: October 2026.
Which loans fit a distressed home?
| Loan | What it does on a distressed home | Key limits |
|---|---|---|
| FHA Limited 203(k) | Purchase plus minor, non-structural repairs | Repairs up to $75,000 since November 4, 2024; 9-month rehab period |
| FHA Standard 203(k) | Purchase plus major work, including structural | $5,000 minimum repair; FHA-approved consultant; 12-month rehab period and up to 12 months of payment reserves |
| Fannie Mae HomeStyle Renovation | Conventional purchase plus repairs to any part of the home, roofs included | Sized on the as-completed appraised value |
| VA Vendee (through VRM) | Purchase of a Vendee-eligible VA-owned home | No mortgage insurance; open to non-veterans and investors |
| Conventional, FHA or VA purchase loan | Standard financing | The home must meet the loan’s condition standards and appraise |
Source: HUD’s 2024 203(k) briefing, Fannie Mae’s HomeStyle page and VRM’s Vendee page (all under Sources).
What blocks financing on a foreclosure?
The obstacle is condition: HUD markets homes as “insured” (eligible for standard FHA) or uninsured, and HomeSteps says some homes are repaired to a financeable standard and others are not. Condos carry a second test: Fannie Mae’s Selling Guide makes a project ineligible when it has unfunded critical repairs costing more than $10,000 per unit due within 12 months, or a special assessment tied to an unremediated critical repair, so some distressed Naples condos sell to cash buyers only.
What should you check before buying a distressed Naples property?
Run these checks before the inspection period ends, because a bank or the Clerk will not. Most are cheap: a Collier County code lien search costs $25 per address, a City of Naples lien request $12.50, and the permit and flood map searches cost nothing.
Data updated: October 2026.
| Check | Where to look | Official URL | Cost |
|---|---|---|---|
| Open permits, unincorporated Collier | Collier CityView portal | Open Collier CityView portal | Free |
| Permits inside the City of Naples | City of Naples Public Portal | Open City of Naples Public Portal | Free, no account |
| Collier code violations and liens | Collier Code Enforcement lien search | Open Collier Code Enforcement lien search | $25 per address |
| Collier code lien relief | Code Lien Relief (Resolution 2023-90) | Open Code Lien Relief (Resolution 2023-90) | $150 application |
| City of Naples liens | Orange Lien Data | Open Orange Lien Data | $12.50; 7 to 10 business days |
| Unpaid taxes and tax certificates | Collier County Tax Collector | Open Collier County Tax Collector | Free |
| Flood zone, effective map | FEMA Flood Map Service Center | Open FEMA Flood Map Service Center | Free |
| Flood zone, proposed map | Collier preliminary FIRM, appeals from August 19, 2026 | Open Collier preliminary FIRM, appeals from August 19, 2026 | Free |
| 50 percent rule history | Collier Floodplain Management | Open Collier Floodplain Management | Free to ask |
| Roof age and insurability | Citizens roof rules; a 4-point inspection | Open Citizens roof rules; a 4-point inspection | Inspection fee |
| Septic and well (Golden Gate Estates) | Florida Department of Health in Collier County | Open Florida Department of Health in Collier County | Well samples about $20 to $30 |
| HOA or condo estoppel certificate | The association, under s. 718.116(8) or s. 720.30851 | Open The association, under s. 718.116(8) or s. 720.30851 | Capped by statute |
| Title search | Title company; Clerk official records | Open Title company; Clerk official records | Varies |
An association must deliver an estoppel certificate within 10 business days; the statute’s base caps ($250, plus $100 for 3-day delivery and $150 for a delinquent account) are adjusted every five years for inflation, so ask for the current fee. Three checks cost buyers the most.
Code liens
Under s. 162.09, code fines can run $250 a day for a first violation and $500 for a repeat, and a recorded order becomes a lien. Collier’s lien relief benchmarks a settlement near 10 percent of assessed value but can deny a new owner whose title policy showed the lien. The City of Naples cut one accrued fine from $13,350 to $1,000 in 2017 (Resolution 2017-13948), contingent on prompt payment.
Flood and the 50 percent rule
In a FEMA flood zone, repairs or improvements costing 50 percent or more of the building’s pre-work market value require the building to meet current elevation rules, per Collier County and the City of Naples. A flooded, unrepaired foreclosure can cross that line. Collier’s effective map dates from February 8, 2024, and its preliminary map, released March 20, 2025, is targeted to take effect in summer 2027.
Roof and insurance
Citizens Property Insurance requires shingle roofs over 25 years old, and tile, metal or concrete roofs over 50, to show at least five years of remaining life on a 4-point or roof inspection. Get an insurance quote on an older bank-owned home before the inspection period ends.
Why are Naples condos the most likely distressed sales?
Because the law now makes old buildings pay for deferred work. Condos were 16 of the 35 Naples deeds into lenders in the 12 months to August 17, 2026. Since SB 4-D (2022) and HB 913 (effective July 1, 2025), buildings of three or more habitable stories need milestone inspections and a structural integrity reserve study (SIRS), due by December 31, 2025.
Data updated: October 2026.
What do the condo laws require in Collier County?
Collier County’s milestone page sets the first inspection at 30 years after the certificate of occupancy, 25 years for buildings within three miles of saltwater, and every 10 years after; the county report fee rose from $50 to $500 per report on January 1, 2026. HB 913 raised the reserve item threshold from $10,000 to $25,000 and let associations pause reserve contributions for up to two budget years to fund milestone repairs. Buyers now get a 7-day cancellation window after receiving the association documents, which must include the milestone summary and reserve study.
What does that mean for prices and assessments?
Reserve funding becomes higher dues or a special assessment, which can push owners to sell or fall behind. Naples condo inventory reached 3,979 in March 2025, up 42.8 percent, with the median down 7.1 percent to $486,000, per Naples-area Realtor data reported by Naples News Now. By May 2026, NABOR reported inventory down 21.1 percent to 2,806, a $450,000 median and 7.7 months of supply, and the Gulf Shore Association of Condominiums told Gulfshore Business that 83 percent of 245 identified Naples buildings had completed their reports by mid-2025. After Hurricane Ian ($2.2 billion of Collier damage), Vanderbilt III condominium owners in Naples reported paying $9 million out of pocket on an $11 million claim. Read the SIRS, milestone report, budget and estoppel first; Fannie Mae’s critical-repair rule can make a building cash only. See Naples condos for sale and Naples beachfront condos.
Do Naples foreclosures make sense for investors?
Sometimes, on annual rentals. HUD’s fiscal 2026 Fair Market Rent for a three-bedroom in the Naples-Marco Island metro is $2,581 a month, but the City of Naples allows rentals under 30 days only three times a year, and taxes, insurance and condo dues decide whether a distressed purchase pays.
Data updated: October 2026.
| Unit size | HUD Fair Market Rent, FY2025 | HUD Fair Market Rent, FY2026 |
|---|---|---|
| Efficiency | $1,362 | $1,396 |
| One-bedroom | $1,596 | $1,797 |
| Two-bedroom | $1,860 | $1,986 |
| Three-bedroom | $2,453 | $2,581 |
| Four-bedroom | $2,662 | $2,805 |
Source: HUD User FY2026 Fair Market Rents, Naples-Marco Island MSA. Collier County’s January 2026 apartment survey put Naples medians at $1,678, $1,964 and $2,318 for one to three bedrooms.
What are the Naples rental rules?
The City of Naples requires rental terms of 30 days or longer, with three shorter rentals a year; unincorporated Collier requires registration under Ordinance 2021-45 to rent under 30 days more than three times a year. Under s. 718.110(13), a condo rental limit binds owners who acquire title after it takes effect, which covers a foreclosure buyer whenever the limit predates the purchase. Stays of six months or less carry Collier’s 5 percent tourist tax plus 6 percent state sales tax; a 6 percent tourist tax is on the November 3, 2026 ballot.
What does a Naples rental cost to carry?
Collier’s general fund levies 3.0107 mills and the City of Naples 1.2300 mills, before school, fire and other levies, so pull the parcel’s TRIM notice and an insurance quote. The 10 percent cap on non-homestead assessment growth resets to just value on a change of ownership (s. 193.1554), so taxes follow your price; Amendment 3, on the November 3, 2026 ballot, would cut that cap to 5 percent.
How do financing and taxes work for investors?
DSCR loans underwrite on rent rather than income, so high taxes, insurance and dues can sink the ratio. Rental buildings depreciate over 27.5 years (IRS Publication 527), and a 1031 exchange requires naming replacement property within 45 days and closing within 180. If a fixer’s numbers fail, compare new construction in Naples.
How do Naples foreclosures compare with Fort Myers and Punta Gorda?
Naples has far fewer. ATTOM ranked the Punta Gorda metro first in the U.S. at 0.50 percent of housing units with a filing in the first half of 2026 and Cape Coral-Fort Myers at 0.35 percent, while the Naples metro did not appear in ATTOM’s ranked lists. Collier also sells in person, where Lee County sells online.
Data updated: October 2026.
| Measure | Naples (Collier County) | Fort Myers (Lee County) | Punta Gorda (Charlotte County) |
|---|---|---|---|
| Mortgage foreclosure sale format | In person at the Main Courthouse | Online, held through the week (Lee Clerk) | Check the Charlotte County Clerk’s sale page |
| Metro foreclosure rate, first half 2026 (ATTOM) | Not in ATTOM’s ranked lists | 0.35%, Cape Coral-Fort Myers metro | 0.50%, highest metro in the U.S. |
| Serious delinquency after Hurricane Ian, Dec 2023 | Not named among rising metros | Rising, one of 3 U.S. metros | Rising, one of 3 U.S. metros |
| 2008 crash | 4.98% of Collier housing units with a filing | 12.03%, Cape Coral-Fort Myers metro, highest in the U.S. | n/a |
| Median single-family price, Sept 2026 (Florida Realtors) | $785,000, Naples metro | see our Fort Myers page | see our Punta Gorda page |
Who should choose which market?
Buyers chasing volume will find more distressed listings in Lee and Charlotte counties; see our Fort Myers and Punta Gorda pages. Buyers who want a distressed home where prices have held are better served in Naples, with thinner supply and higher prices.
How Domain Realty Group helps Naples buyers with distressed property
Domain Realty Group, the #1 team in Southwest Florida since 2012, with 4,000+ team transactions and $2.5B+ team volume, is led by Jesse McGreevy and Marc Comisar, Top 1% Real Estate Agents Nationally Since 2008. On a distressed Naples home we pull the county sale and deed history, run the Collier or City of Naples lien, permit and flood checks before the inspection period ends, write offers on the lender’s addendum, and track short-sale approvals against the rider deadlines.
Data updated: October 2026.
Ready to buy a bank-owned or short-sale home in Naples?
Tell us the price range, area and whether you need a loan, and an agent from Domain Realty Group, the #1 team in Southwest Florida since 2012, checks each listing first. Contact our team, call 239-441-2816, or meet our agents. For Jesse and Marc’s guide to buying a home in Naples with buyer representation, see their Naples home buying guide.
Thinking of selling a Naples home before it reaches foreclosure?
An owner with equity can usually sell ahead of the auction, and the Naples single-family median was $785,000 in September 2026 per Florida Realtors. Start with a Domain Realty Group home valuation from the #1 team in Southwest Florida since 2012.
Where to go next: Naples homes for sale and communities, all Naples communities, Naples luxury homes for sale, Naples waterfront homes for sale and Naples golf homes for sale.
Frequently Asked Questions about Naples foreclosures
These answers cover the questions Naples and Florida buyers search most about foreclosures, from timelines, auctions and liens to tax deeds, bank-owned homes, short sales and title insurance. Each figure comes from Collier County records, the Collier Clerk, Florida Statutes or ATTOM, dated in the sections above.
How long does a foreclosure take in Florida?
Florida is a judicial foreclosure state, so each case runs through circuit court: if the lender uses the expedited show-cause route, that hearing cannot come sooner than 45 days after the complaint is served, then the sale follows 20 to 35 days after judgment and a 10-day objection window. ATTOM put the national average at 563 days in the second quarter of 2026.
Can you inspect a foreclosure before the auction?
Generally no. The Collier County Clerk sells every foreclosure “as is,” with no warranty and no inspection right, and the owner or a tenant may still occupy it. Bank-owned and short-sale homes are different: the Florida contract’s inspection period lets a buyer inspect and cancel, which is why financed buyers stick to bank-owned listings.
Do you need cash for a Collier County foreclosure auction?
In practice, yes. The winner posts a 5 percent deposit at the sale and pays the balance, the registry fee (3 percent of the first $500 plus 1.5 percent of the rest) and costs by 10:30 a.m. the next business day. On a $400,000 bid, the registry fee and deed stamps add $8,807.50.
Does a tax deed wipe out the mortgage?
Taxes come first: s. 197.122 makes them “a first lien, superior to all other liens,” and mortgage holders of record get notice of a tax deed application under s. 197.502 so they can pay the taxes before the sale. Whether any lien survives a particular tax deed is a title question, because the Collier Clerk gives no title guarantee.
What is the difference between a short sale and a foreclosure?
In a short sale the owner still holds title and sells for less than the loan with every lender’s written approval, which the Florida rider gives a 90-day default deadline. In a foreclosure the lender wins a court judgment and the Clerk sells the home at auction, usually to the lender, which later resells it as bank-owned.
Are there foreclosures for sale in Naples right now?
A few at a time. Lenders took 35 Naples homes and resold 16 in the 12 months to August 17, 2026, per Collier County records, so bank-owned listings appear sporadically. Use the filtered listing links at the top of this page, and ask us to flag listings whose remarks say bank owned, REO or short sale.
Who pays title insurance on a Naples bank-owned home?
In Naples the buyer customarily pays for the owner’s title insurance policy, and on a bank-owned home it matters more than usual: banks usually convey by special warranty deed, covering only the years the bank owned the property. Confirm in the lender’s addendum who pays each closing cost, since some banks name their own closing agent.
Is Florida a judicial foreclosure state?
Yes. A Florida lender must sue in circuit court under chapter 702 of the Florida Statutes and win a final judgment before any sale, and chapter 45 governs the sale itself. Under s. 45.031(1)(a), the Clerk’s sale is set 20 to 35 days after the judgment unless the plaintiff consents to a later date.
Does Florida have a redemption period after foreclosure?
No post-sale period. Under s. 45.0315, the owner or a subordinate lienholder can cure the debt and stop the sale only until the later of the Clerk filing the certificate of sale or a time set in the judgment; “otherwise, there is no right of redemption.” Once that point passes, the sale stands.
Are foreclosure auctions in Collier County online?
No. The Collier Clerk’s foreclosure sales page, updated October 5, 2026, says all foreclosure sales are held in person at the Main Courthouse, 3315 Tamiami Trail East, Naples, in the first-floor multipurpose room on the annex side. The online Foreclosure Auction Calendar is for finding sales, not bidding, unlike Lee County’s online sales.
Who conducts foreclosure auctions in Florida?
The Clerk of the Circuit Court in each county. In Naples that is the Collier County Clerk of the Circuit Court and Comptroller, Crystal K. Kinzel, whose office runs both the court-ordered mortgage foreclosure sales and the tax deed sales at the courthouse. The Tax Collector, a separate office, runs the annual online tax certificate sale.
Who can bid at a Collier County foreclosure auction?
Anyone who can pay. Bidding is open and the highest bidder wins, but the winner must post a 5 percent deposit and pay the balance by 10:30 a.m. the next business day. The foreclosing lender usually bids its judgment as credit, which is why most Naples foreclosures end with the home going to the lender.
How do I find foreclosure auctions in Collier County?
Use the Collier Clerk’s Court Events search, choose “Foreclosure Sales” as the event type and pick a date to see the case numbers. Each sale’s notice is published once a week for two consecutive weeks, the second at least 5 days before the sale, and filed with the Clerk at least 24 hours ahead.
How do I find out if a home is in foreclosure?
Look for a lis pendens and a foreclosure case on the Collier Clerk’s official records and court records. A lis pendens is the recorded notice that a lawsuit affects the property; under s. 48.23 it lasts one year from the start of the action unless the claim rests on a recorded instrument, such as a mortgage.
How long does it take to buy a house at a Florida foreclosure auction?
About two weeks from the bid to title in a clean Collier sale. The balance is due by 10:30 a.m. the next business day, the Clerk files the certificate of sale usually within a day, and if no one objects within 10 days, the Clerk files the certificate of title and title passes to the buyer.
Can a Florida foreclosure sale get canceled after the auction?
Only through an objection or a court order. Under s. 45.031(8), any party may object to the bid amount within 10 days after the Clerk files the certificate of sale. Before that filing the owner can still cure the debt under s. 45.0315, which is why Collier sales are sometimes cancelled at the last minute.
Can you refuse a house if you win it at a foreclosure auction?
Not without losing money. A winner who does not pay the balance on time loses the sale, and under s. 45.031(3) the Clerk readvertises the property and pays the sale costs out of the 5 percent deposit. On a $400,000 winning bid that deposit is $20,000, so research title before you raise your hand.
Do liens survive a foreclosure auction in Florida?
Some do. Unpaid property taxes are “a first lien, superior to all other liens” under s. 197.122, a properly noticed IRS lien can be redeemed for 120 days after the sale, and a new condo owner is jointly liable for past-due assessments under s. 718.116(1)(a). A first mortgage can also survive a junior lender’s or association’s foreclosure.
Will I owe the condo association after buying a Naples foreclosure?
Probably. Under s. 718.116(1)(a), a new unit owner is jointly and severally liable with the previous owner for unpaid assessments. Only a first mortgage lender that named the association in the case gets the cap of 12 months of assessments or 1 percent of the original debt, whichever is less. Order an estoppel certificate, due within 10 business days.
How much is the state deed tax in Florida?
Documentary stamp tax on a deed is $0.70 per $100 of consideration under s. 201.02(1)(a), and Collier County uses that rate. At a Collier foreclosure sale the Clerk collects it on the bid before issuing the certificate of title: $2,800 on a $400,000 bid, on top of the $6,007.50 court registry fee.
How long do tenants get after a Naples foreclosure?
At least 90 days. Under s. 83.5615, the successor in interest after a foreclosure must give a bona fide tenant a notice to vacate at least 90 days before its effective date, and a tenant with a lease signed before the foreclosure notice may stay to the end of the lease unless the buyer will live there.
Is Florida a tax deed or a tax lien state?
Both, in sequence. The Collier Tax Collector first sells tax certificates online, with bidders cutting the interest rate in quarter-point steps under s. 197.432 from an 18 percent maximum. If the taxes stay unpaid 2 years from April 1 of the issue year, the holder can apply for a tax deed and the Clerk auctions the property.
What is a tax deed application in Florida?
It is the certificate holder’s request to force a sale. Under s. 197.502, a holder other than the county may apply after 2 years have passed since April 1 of the certificate’s issue year, paying a $75 Tax Collector fee plus online costs. The Clerk records a notice of application, effective one year, and notifies titleholders and lienholders.
How is the opening bid in a tax deed sale calculated in Florida?
Under Florida Administrative Code Rule 12D-13.063, the opening bid adds the certificates, delinquent and current taxes, the Tax Collector’s, sheriff’s and Clerk’s fees, and interest at 1.5 percent a month. On homestead property, s. 197.502(6) adds one-half of the latest assessed value, so homestead parcels open far higher than the tax debt alone.
Are REO properties sold as-is in Florida?
Usually. Banks and agencies sell bank-owned homes as is, often on the Florida “As Is” contract, which lets the buyer inspect and cancel within the inspection period but gives the seller no duty to repair. Florida real estate attorneys note that a foreclosing lender that never lived in the home falls outside the Johnson v. Davis disclosure duty.
Can you finance a bank-owned home in Naples?
Yes, if the home qualifies. FHA’s Limited 203(k) covers up to $75,000 of repairs and the Standard 203(k) requires at least $5,000 of work, Fannie Mae’s HomeStyle loan is sized on the as-completed value, and VA Vendee loans fit eligible VA homes. Fannie Mae bars condo projects with unfunded critical repairs over $10,000 per unit.
How long does a short sale take in Florida?
Under the default terms of the Florida Realtors and Florida Bar short sale rider, the lender has 90 days from the contract date to approve, and closing falls 45 days after the buyer receives approval, so about 135 days, or four and a half months. Without approval, the contract ends automatically 30 days after the deadline.
Can you sell a house in foreclosure in Florida?
Yes, until the certificate of sale. The owner can sell outright if the price pays off the loan, or as a short sale with the lender’s written approval. Under s. 702.06 a deficiency on an owner-occupied home cannot exceed the debt minus fair market value, and Fannie Mae’s wait to borrow again is 4 years, not 7.
How long after a foreclosure can you buy a house?
For a Fannie Mae-backed loan, 7 years after a foreclosure, or 3 years with documented extenuating circumstances, under Selling Guide B3-5.3-07. After a short sale or a deed in lieu the wait is 4 years, or 2 with extenuating circumstances, which is a main reason owners sell before the auction.
Are foreclosures always cheaper than traditional homes?
Not always. Naples lender resales in the 12 months to August 17, 2026 had a $440,500 median against $615,000 for 8,129 qualified home sales, but the mix leaned to condos and East Naples. Some sold in the millions. Price each one against nearby sales after repair, insurance, liens and association debt.
Do foreclosures have clear title?
Not automatically. The Clerk’s certificate of title carries no warranty, and banks usually sell by special warranty deed, which covers only the years the bank owned the home. Taxes, some government liens and association balances can follow the property, so order a title search and an owner’s title policy, which a Naples buyer customarily pays for.
What is the foreclosure rate in Florida?
Florida had the highest state rate in the U.S. in the first half of 2026: 0.27 percent of housing units, or 1 in 373, with 27,494 properties with a filing, per ATTOM. For all of 2025 the rate was 1 in 230. Naples is far below that: 35 lender deeds in a year on the Collier County record.
Do I need a Realtor to buy a foreclosure in Naples?
For HUD homes, yes: HUD Home Store bids must come through a HUD-registered broker. HomePath homes also go through an agent, and banks deal through their listing brokers. Domain Realty Group, the #1 team in Southwest Florida since 2012, represents Naples buyers on bank-owned, HUD and short-sale purchases and runs the lien and title checks before the offer.
What our clients say about Domain Realty Group
★★★★★ “Marc has been a great help in securing a great price for our home during its build phase. Negotiated a much better deal from the builder.”
Verified Google review. Michael Gatz, on working with Marc Comisar of Domain Realty Group.
★★★★★ “Marc was terrific to work with. His knowledge of the area, community and builder were excellent. He and his staff were well organized and made the process easy. I highly recommend Marc and his team.”
Verified Zillow review. mhhade, on working with Marc Comisar of Domain Realty Group.
★★★★★ “Marc’s knowledge of the Southwest Florida real estate market is unmatched. He took the time to understand exactly what I was looking for in a home and quickly identified properties that checked all my boxes.”
Verified Google review. Christopher Dietz, on working with Marc Comisar of Domain Realty Group.
Read every review on our Google Business Profile.
About Domain Realty Group in Naples
Domain Realty Group is a Southwest Florida real estate team with its Naples office at 9180 Galleria Ct #200, Naples, FL 34109, and offices in Bonita Springs and Fort Myers, working Collier, Lee and Charlotte counties. Domain Realty Group has been the #1 team in Southwest Florida since 2012, with $2.5 billion in team production and more than 4,000 transactions. We tracked every deed into a lender recorded in the 14 Naples ZIP codes since 2005 to build this page. The team is led by Jesse McGreevy and Marc Comisar, with over 45 years of combined direct experience; learn about Domain Realty Group.
Domain Realty Group
Naples office: 9180 Galleria Ct #200, Naples, FL 34109
Bonita Springs and Estero office: 24031 S Tamiami Trl #101, Bonita Springs, FL 34134
Fort Myers office: 8290 College Parkway Unit 201, Fort Myers, FL
239-441-2816
Brokered by Domain Realty, a licensed Florida real estate brokerage. Florida Real Estate Commission (FREC) licensed. All agents are licensed Florida real estate professionals.
Sources
No portal or other brokerage is cited, by policy; Auction.com and Xome terms come from their own help pages and are not linked.
County records and the Collier Clerk
- Collier County Property Appraiser public sales and parcel files (bundle dated August 29, 2026), accessed October 22, 2026.
- Collier Clerk, Foreclosure Sales, accessed October 22, 2026.
- Collier Clerk, Tax Deed Sales, accessed October 22, 2026.
Florida Statutes
- 45.031, judicial sales, accessed October 22, 2026.
- 45.0315, right of redemption, accessed October 22, 2026.
- 45.032, surplus, accessed October 22, 2026.
- 702.036, finality of judgment, accessed October 22, 2026.
- 702.06, deficiency, accessed October 22, 2026.
- 95.11, limitations, accessed October 22, 2026.
- 718.116, condo assessments and estoppel, accessed October 22, 2026.
- 720.3085, HOA assessments, accessed October 22, 2026.
- 83.5615, tenants after foreclosure, accessed October 22, 2026.
- 197.122, tax liens, accessed October 22, 2026.
- 197.502, tax deed applications, accessed October 22, 2026.
- 197.542, tax deed sales, accessed October 22, 2026.
- 501.1377, foreclosure rescue, accessed October 22, 2026.
- 718.110, condo amendments, accessed October 22, 2026.
- 193.1554, non-homestead cap, accessed October 22, 2026.
- 162.09, code fines, accessed October 22, 2026.
Federal agencies and loan programs
- IRS, Internal Revenue Manual 5.12.5, redemptions, accessed October 22, 2026.
- IRS, Topic 431, canceled debt, accessed October 22, 2026.
- IRS, Publication 527, accessed October 22, 2026.
- IRS, like-kind exchange fact sheet, accessed October 22, 2026.
- HUD, Mortgagee Letter 2022-01, accessed October 22, 2026.
- HUD, asset manager contacts, accessed October 22, 2026.
- HUD, Good Neighbor Next Door fact sheet, accessed October 22, 2026.
- HUD, 203(k) 2024 changes briefing, accessed October 22, 2026.
- HUD User, FY2026 Fair Market Rents, Naples-Marco Island, accessed October 22, 2026.
- Fannie Mae Selling Guide B3-5.3-07, waiting periods, accessed October 22, 2026.
- Fannie Mae Selling Guide B4-2.1-03, ineligible projects, accessed October 22, 2026.
- Fannie Mae, HomeStyle Renovation, accessed October 22, 2026.
- VRM, Vendee financing, accessed October 22, 2026.
Collier County and City of Naples
- Collier County, milestone inspections, accessed October 22, 2026.
- Collier County, code lien search, accessed October 22, 2026.
- Collier County, proposed flood map news, August 19, 2026, accessed October 22, 2026.
- Collier County, short-term rental registration, accessed October 22, 2026.
- City of Naples, short-term rental restrictions, accessed October 22, 2026.
- City of Naples, Resolution 2017-13948, accessed October 22, 2026.
- City of Naples, FY 2025-26 budget millage, accessed October 22, 2026.
- Collier Clerk, county millage rates, accessed October 22, 2026.
- Collier County Tax Collector, tourist tax, accessed October 22, 2026.
- Collier County Housing, January 2026 apartment survey, accessed October 22, 2026.
- U.S. Census Bureau, QuickFacts, accessed October 22, 2026.
Insurance, health, state and neighboring counties
- Citizens Property Insurance, roof rules, accessed October 22, 2026.
- Florida Department of Health in Collier County, septic systems, accessed October 22, 2026.
- Florida Attorney General, mortgage fraud FAQ, accessed October 22, 2026.
- Lee County Clerk, foreclosure sales, accessed October 22, 2026.
- Hillsborough County Tax Collector, tax certificate buyers, accessed October 22, 2026.
Market data and news
- Florida Realtors, HB 913 becomes law, accessed October 22, 2026.
- Florida Realtors, September 2026 MSA summary, accessed October 22, 2026.
- Florida Realtors, September 2026 single-family detail, accessed October 22, 2026.
- NABOR, May 2026 statistics, accessed October 22, 2026.
- ATTOM, 2026 midyear foreclosure report, accessed October 22, 2026.
- ATTOM, states with largest REO increases, first half 2026, accessed October 22, 2026.
- ATTOM, Collier County data, accessed October 22, 2026.
- HousingWire, 2025 foreclosure filings, accessed October 22, 2026.
- HousingWire, MBA delinquency, second quarter 2026, accessed October 22, 2026.
- Fort Myers Beach Talk, 2008 RealtyTrac counts, accessed October 22, 2026.
- Business Observer, Naples sales prices falling, accessed October 22, 2026.
- Business Observer, Gulf Coast foreclosures 2009, accessed October 22, 2026.
- HousingWire, disasters and delinquencies, December 2023, accessed October 22, 2026.
- Gulfshore Business, Naples condo market, July 2026, accessed October 22, 2026.
- Naples News Now, Vanderbilt III repair bill, accessed October 22, 2026.
- Naples News Now, March 2025 inventory, accessed October 22, 2026.
- National Weather Service Miami, Hurricane Ian summary, accessed October 22, 2026.
Contracts and case law
- Attorneys’ Title Fund Services, Florida contracts with Rider G, accessed October 22, 2026.
- Bush v. Whitney Bank, Fla. 5th DCA 2017, accessed October 22, 2026.
- Barnes Walker, seller disclosure in as-is contracts, accessed October 22, 2026.